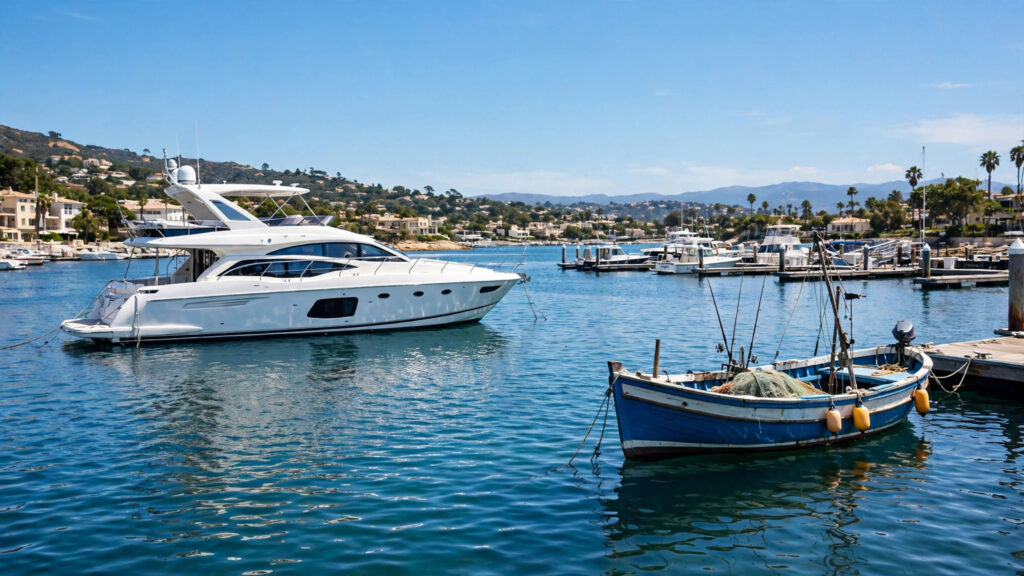
Boat insurance is one of the cheapest policies in the insurance world for small craft, and one of the priciest once yachts enter the picture. In 2026, most recreational boat owners pay between $200 and $500 per year, and a useful rule of thumb is that premiums run about 1 to 2 percent of the boat value annually. A small fishing boat might cost $150 a year to insure while a 45 foot yacht can run $5,000 or more. This guide breaks down average costs by boat type and value, explains the difference between liability only and full coverage, and covers the factors and discounts that move your premium.
Average Boat Insurance Cost by Boat Type
| Boat type | Typical value | Average annual premium |
|---|---|---|
| Small fishing boat or jon boat | $5,000 to $15,000 | $100 to $300 |
| Personal watercraft (Jet Ski, WaveRunner) | $5,000 to $20,000 | $100 to $500 |
| Pontoon boat | $15,000 to $40,000 | $200 to $500 |
| Bowrider or runabout | $20,000 to $60,000 | $300 to $600 |
| Ski and wake boat | $30,000 to $100,000 | $400 to $900 |
| Sailboat under 30 feet | $15,000 to $75,000 | $200 to $700 |
| Cabin cruiser | $50,000 to $200,000 | $500 to $2,000 |
| Yacht, 40 feet and up | $200,000 and up | $1,000 to $5,000 or more |
Viewed by value instead of type, the pattern is consistent: a $10,000 boat costs roughly $200 to $400 a year to insure, a $50,000 boat roughly $500 to $1,200, and a $200,000 boat roughly $1,500 to $3,500. High performance boats break the pattern upward because speed is the single most expensive risk factor in marine underwriting.
Liability Only vs. Full Coverage
Liability only policies
A liability policy pays for damage and injuries you cause to other people and their property, plus related legal defense. It does not pay to repair or replace your own boat. Liability only coverage is the cheapest way to satisfy a marina or lender requirement and can cost well under $200 a year for small boats, but one collision with the dock or a storm sinking leaves the entire loss on you.
Full coverage policies
Full coverage adds hull protection for your own vessel: collision, theft, fire, storm damage, and sinking, usually with medical payments, uninsured boater coverage, and optional towing. This is the structure lenders require on financed boats. Expect full coverage to cost roughly double a liability only premium for the same boat, which is still modest for smaller craft.
Useful add ons
Towing and on water assistance typically adds $30 to $100 a year and pays for itself with one tow. Other common options include personal effects and fishing gear coverage, fuel spill and wreck removal coverage, hurricane haul out reimbursement, and trailer coverage.
What Drives Your Premium Up or Down
- Boat value and type: More value means more to replace. High performance and offshore boats pay the most per dollar of value.
- Horsepower and speed: Insurers price speed aggressively; very fast boats may need specialty carriers.
- Navigation area: Coastal and hurricane exposed waters cost more than inland lakes. Florida and Gulf Coast premiums sit at the top of the national range.
- Boat age and condition: Older boats may need a marine survey before an insurer will offer full coverage.
- Your experience and record: Years of boating, safety course completion, and a clean claims and driving record all earn better rates.
- Storage and season: Keeping the boat in a marina versus on a trailer, and laying it up for winter, changes the risk profile.
- Deductible: Raising a deductible from $500 to $1,000 can cut the premium noticeably, sometimes by 10 to 20 percent.
Is It Worth It? What Claims Actually Cost
Owners sometimes question insuring a paid off boat, so it helps to price the risks instead of the premium. Industry figures put the average boating accident cost above $11,000 per incident once property damage and injuries are combined, and a liability judgment after a serious injury can reach six figures. A sinking at the dock or a storm total loss destroys the full value of the boat, while wreck removal and fuel spill cleanup, which authorities can require you to pay for, add thousands more on top of the loss itself. Against those numbers, a $300 annual premium on a $30,000 boat is buying protection against expenses that would take years of premiums to self insure. The calculus is weakest for very cheap boats worth a few thousand dollars, where some owners reasonably carry liability only and accept the hull risk. For anything you could not replace out of pocket without pain, full coverage earns its cost.
Agreed Value vs. Actual Cash Value
This single policy word decides what a total loss pays. An agreed value policy locks in the amount you and the insurer set when the policy starts; if the boat is destroyed, you receive that amount with no depreciation deducted. It costs more and is usually the better choice for newer or well kept boats. An actual cash value policy pays the depreciated market value at the time of loss, which can be thousands less than you expected on an older boat. Read which one you are buying before you compare quotes, because a cheaper actual cash value premium is not the same product.
Regional Differences: Why Florida Pays More
Where a boat lives is nearly as important as what it is. Florida owners pay the highest premiums in the nation because hurricane exposure, year round boating, theft rates, and crowded waters stack every risk factor at once; a cruiser that costs $700 a year on an inland lake in the Midwest can cost $1,500 or more in South Florida. Gulf Coast and Atlantic hurricane zones price above average for the same reason, and some insurers restrict new policies when a named storm approaches. At the other end, inland northern boats benefit from short seasons and winter storage, and lay up discounts reflect that lower exposure. Sailboats racing regularly may pay more than identical cruising boats, and boats kept in the water year round in warm salt water carry higher hull risk than trailered freshwater boats. When comparing quotes, make sure each insurer is pricing the same navigation territory, since a policy limited to inland and coastal waters costs less than one covering offshore passages to the Bahamas or beyond.
Ways to Save on Boat Insurance
- Complete a recognized boating safety course; many insurers discount 5 to 10 percent.
- Take the lay up discount if your boat sits out the winter, since a stored boat is a lower risk.
- Bundle with your home or auto insurer and ask about multi policy pricing.
- Choose a higher deductible you could genuinely pay.
- Limit your navigation area to the waters you actually use.
- Install safety and anti theft equipment, and keep a clean claims record.
- Compare at least three quotes, including a marine specialist, since general insurers price boats inconsistently.
The Bottom Line
Most boat owners will pay $200 to $500 a year in 2026, roughly 1 to 2 percent of the boat value, with small boats under $300 and yachts running into the thousands. Full coverage costs about twice liability only but protects the asset itself. Choose agreed value coverage for a boat you could not afford to replace, mind the deductible, and take the safety course discount; marine insurance is one market where small steps reliably lower the bill.
Frequently Asked Questions
How much is boat insurance for a $30,000 boat?
Expect roughly $300 to $700 per year for full coverage on a typical $30,000 runabout or pontoon, following the rule of thumb of 1 to 2 percent of value annually. Liability only would cost less.
Is boat insurance required by law?
Most states do not require boat insurance by law, but lenders require it on financed boats and many marinas require liability coverage to rent a slip. A few states mandate liability coverage for certain vessels.
What is the difference between agreed value and actual cash value?
Agreed value pays the fixed amount written in the policy after a total loss, with no depreciation. Actual cash value pays the depreciated market value at the time of loss, which is less, though the premium is cheaper.
Does homeowners insurance cover my boat?
Only in a limited way. Home policies usually cover small, low horsepower boats on inland waters with low coverage limits. Most boats need a dedicated marine policy for real protection.