The short answer: it’s the extra layer that pays when a business claim exceeds your primary limits
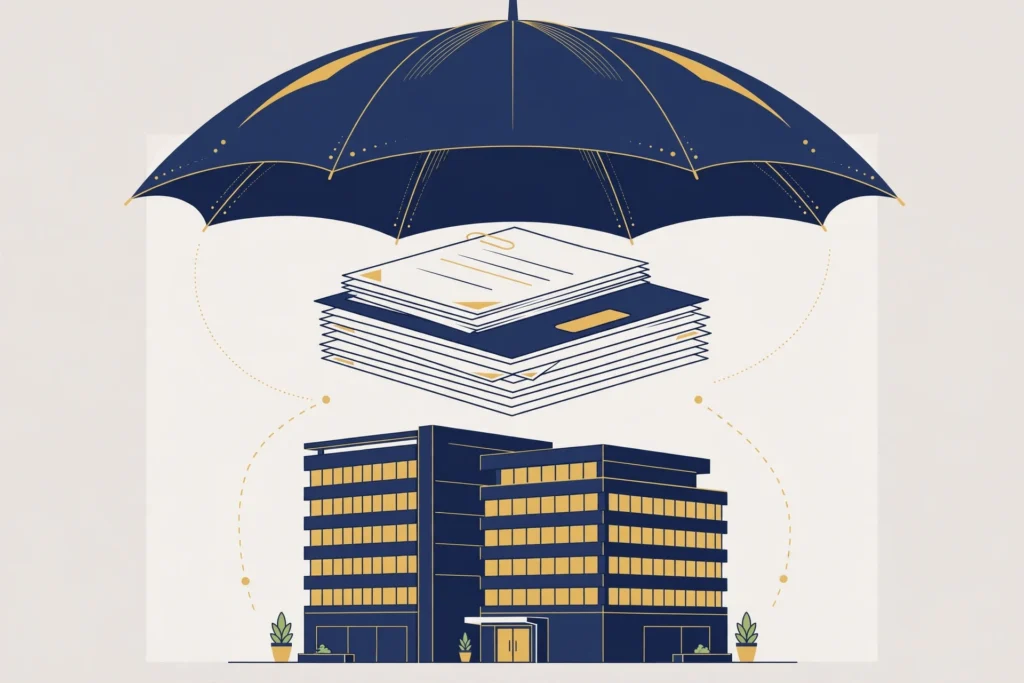
Umbrella liability insurance for business — sold as commercial umbrella insurance — doesn’t replace any policy you have. It sits above them: when a covered claim exhausts your general liability, commercial auto, or employer’s liability limits, the umbrella pays the rest, up to its own limit.
Think of it as a tower: your primary policies are the ground floor — say $1M each for general liability and commercial auto — and the umbrella is one shared $1M–$5M roof stretched across all of them. A catastrophic claim draws from the ground floor first, then the roof.
This guide explains the mechanics: how the stacking works in practice, which claims actually trigger the umbrella, how per-occurrence and aggregate limits apply, and where the coverage stops.
How commercial umbrella stacks over primary policies
Every commercial umbrella policy has a schedule of underlying insurance — the list of primary policies and minimum limits it requires. A typical schedule looks like this:
| Underlying policy | Typical required minimum limit | Umbrella’s role |
|---|---|---|
| Commercial general liability (CGL) | $1M per occurrence / $2M aggregate | Pays covered amounts above $1M per occurrence |
| Commercial auto liability | $1M combined single limit | Pays covered amounts above $1M |
| Employer’s liability (part of workers’ comp) | $500K–$1M | Pays covered employer-liability suits above the limit |
Here’s the stacking in action. Suppose a company delivery van runs a red light and seriously injures two people in another car. Medical costs, lost wages, and pain-and-suffering damages total $2.4 million, and the company’s commercial auto policy has a $1 million limit. The auto insurer pays its $1 million; the commercial umbrella pays the remaining $1.4 million (assuming a large enough umbrella limit). Without the umbrella, the business owes $1.4 million out of pocket.
Two mechanics matter. First, the umbrella only responds to covered claims — if the underlying policy excludes the loss, the umbrella excludes it too. Second, you must maintain the scheduled underlying limits: lower your general liability to save premium and many umbrellas make you cover the gap yourself before paying a dollar.
What claims trigger a commercial umbrella
The umbrella triggers on severity, not frequency. Routine claims never touch it. The triggers are the catastrophic tail events:
- Severe bodily injury to third parties. The most common trigger by far. Multi-vehicle commercial auto accidents, serious premises injuries (falls from height, machinery accidents at your facility), and injuries caused by your products or completed work.
- Multi-claimant events. One incident, many injured people. A fire your work started in a commercial building, a contaminated product batch, a structural failure — each victim’s damages stack toward (and past) your primary limits.
- Large property damage. Your contractor’s torch starts a fire that damages a $3 million commercial building. Your CGL pays its $1M; the umbrella covers the rest.
- Personal and advertising injury. Libel, slander, false arrest, or copyright claims in your advertising that escalate beyond nuisance value. Coverage here depends on the underlying CGL including it and the umbrella following form.
- Employer’s liability suits. When an injured employee (or their family) sues the company outside the workers’ comp system — alleging, for example, gross negligence — the employer’s liability portion can pierce its limits and reach the umbrella.
Every trigger involves damages that can plausibly exceed $1 million — that’s the product’s entire economic logic: insuring the tail where one event threatens the business. If your commercial auto liability limits look thin, the umbrella is the backstop, but raising the auto limit itself is sometimes cheaper.
How the limits work: per occurrence, aggregate, and retained limit
Commercial umbrella limits have more moving parts than personal ones. Three terms control everything:
Per-occurrence limit
The most the umbrella pays for a single incident. A $2M per-occurrence umbrella pays at most $2M above the underlying limit for one accident, no matter how many claimants it involves.
Aggregate limit
The most the umbrella pays across all incidents in the policy year. Many commercial umbrellas are written as $2M per occurrence / $2M aggregate (or $4M aggregate), meaning two $2M catastrophes in one year could exhaust the policy. Businesses with high claim frequency in severe categories — fleets, contractors — should weigh a higher aggregate.
Retained limit (self-insured retention)
Some umbrellas include a retained limit — a deductible-like amount, often around $10,000 — applying to claims the umbrella covers but the underlying policy doesn’t (drop-down situations). For standard claims that pierce the underlying limits, there’s typically no additional deductible: the underlying limit is the deductible, in effect.
Defense costs matter too. Most commercial umbrellas pay defense costs in addition to the limit — but once the limit is exhausted by a judgment or settlement, the duty to defend usually ends. Complex liability defense can run into six figures on its own, so confirm how your policy handles it.
Follow form vs. drop-down: two flavors of umbrella
Not all commercial umbrellas behave identically when a claim falls between policies:
- Follow-form (pure excess) umbrella. Mirrors the underlying policy’s coverage exactly, just with a higher limit. Simpler, and it’s what most small and mid-size businesses actually buy. If the primary policy excludes it, the umbrella excludes it.
- True umbrella with drop-down coverage. Can cover certain claims the underlying policy excludes or doesn’t address — for example, a covered occurrence outside the primary policy’s territory — subject to the retained limit. Broader, usually pricier, and more common in large commercial programs.
When comparing quotes, ask which type you’re offered — a cheaper follow-form quote and a pricier true-umbrella quote aren’t the same product.
What it doesn’t cover
The umbrella inherits underlying exclusions and typically adds its own:
- Professional liability / errors and omissions (needs a separate E&O policy)
- Employment practices claims like discrimination or wrongful termination (needs EPLI)
- Workers’ compensation benefits themselves (the umbrella sits over employer’s liability suits, not the comp system)
- Pollution and environmental damage (usually excluded; endorsed back only for businesses that need it)
- Intentional acts, fraud, and criminal conduct
- Property you own, rent, or have in your care (first-party property needs commercial property coverage)
- Aviation exposures, including commercial drones, unless specifically endorsed — drone operators should carry dedicated drone liability insurance rather than assuming the umbrella reaches it
Also verify each vehicle class is scheduled — an umbrella over standard commercial autos may not extend to a company-owned RV used as a mobile showroom. Check how RV liability coverage coordinates with your commercial program first.
The economics: why businesses buy the roof, not just the walls
Commercial umbrella insurance exists because liability severity is skewed: most claims are small, but a tiny fraction are enormous, and those enormous claims cluster in exactly the categories businesses can’t avoid — vehicles, premises, products. Raising every primary policy to $5M would be expensive and inefficient, because you’d be paying high primary rates for coverage you almost never use.
The umbrella solves this with wholesale pricing on the tail: catastrophic claims are rare, so the top layer costs far less per dollar than the first million. That’s why a $2M umbrella often costs a fraction of the $1M general liability policy beneath it. (The same curve applies personally; see typical umbrella costs per month.)
Size the umbrella to your realistic worst case — the multi-claimant accident, the building fire, the product failure — not your average claim. Review it when the business changes shape: new vehicles, locations, product lines, or bigger contracts.
FAQs
Does commercial umbrella insurance cover all my business policies?
It covers the liability policies listed in its schedule of underlying insurance — typically general liability, commercial auto, and employer’s liability. It does not cover property insurance, workers’ comp benefits, professional liability, or any policy not scheduled. Read the schedule; it’s the actual table of contents of your coverage.
What happens if a claim exceeds both my primary and umbrella limits?
The business pays the remainder out of its own assets — and depending on the business structure and the claim, owners’ personal assets can be exposed too. This is why sizing the umbrella to a realistic worst case matters more than hitting a round number.
Can I buy a commercial umbrella from a different insurer than my primary policies?
Sometimes, but most insurers prefer or require the umbrella to sit over primaries they also wrote, since shared claims handling is cleaner when a loss pierces layers. Standalone umbrellas over another carrier’s primaries exist but are harder to place and can complicate a large claim.
How do aggregate limits work if I have multiple claims in one year?
Each covered claim draws from the same annual aggregate. Two $1.5M umbrella-layer losses in one year against a $2M aggregate leaves the second claim $1M short. High-severity businesses should consider whether their aggregate — not just per-occurrence limit — fits their risk.
Is umbrella insurance worth it for a business with no prior claims?
A clean claims history is exactly when umbrella coverage is cheapest — and past calm predicts nothing about tail risk. The product insures against the one event you haven’t had yet. Most businesses buy it precisely because their loss history gives no warning before a catastrophic claim.